Glebors Global Finance has always advocated the entrepreneurial spirit of pioneering, adventurous and hardworking. Relying on the unique perspective, Glebors has launched various special issues in terms of the economy and finance, which has provided much more assistance to government decision-makers and business leaders.
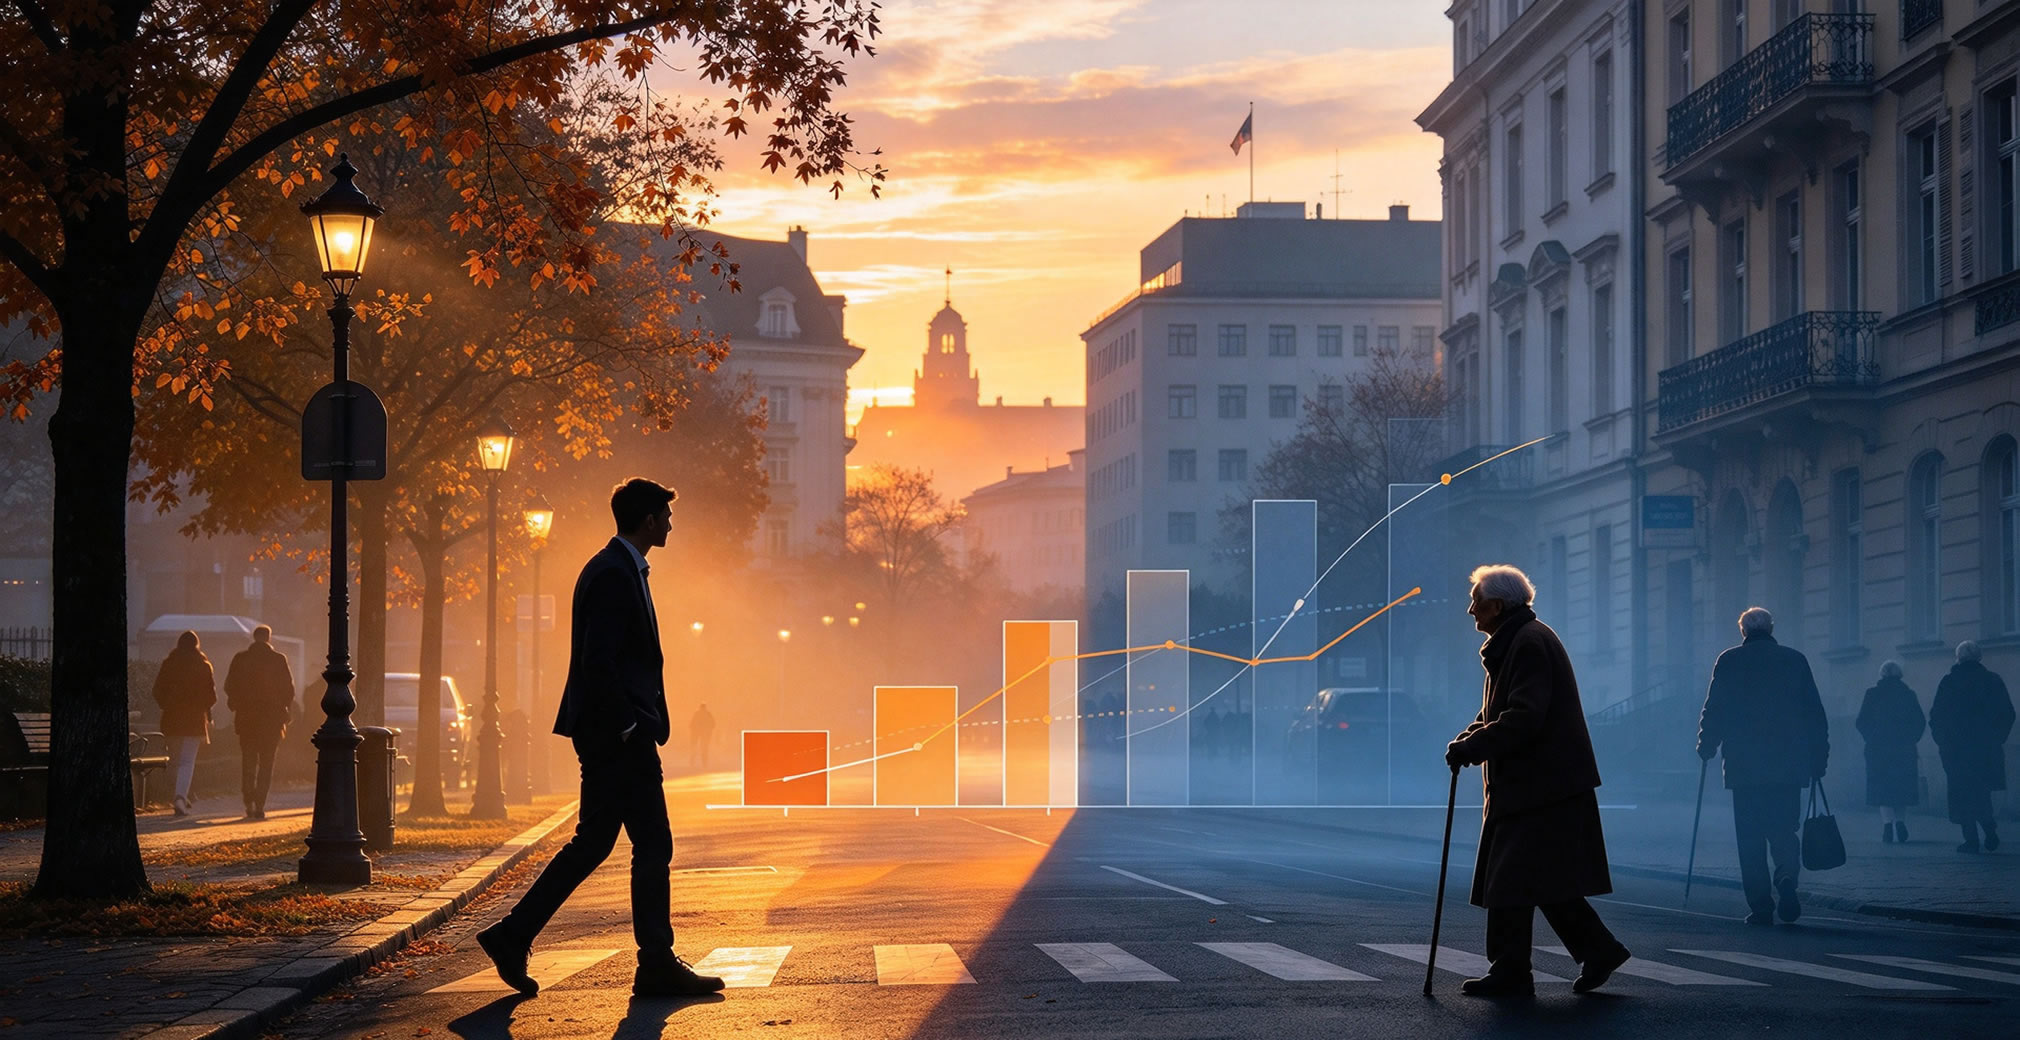
The world's retirement systems are losing a race against biology. People are living years longer than any actuarial table written in the 1950s could have foreseen, while birth rates have collapsed so far below replacement that the pool of workers financing each retiree is starting to shrink in absolute terms. The two forces have been building for decades, and they are now converging with a precision that pension executives no longer try to soften.
The language they reach for is revealing. Sebastien Betermier, executive director of the International Centre for Pension Management, describes the situation as a "ticking time bomb." He points to funds whose members have been retired for nearly half a century — beneficiaries who are now 107 or 108 years old. Each additional year of life is, in actuarial terms, an additional liability that someone must eventually pay. "Think about the cost that it imposes actually on the next generation," he says.
That sentence captures the uncomfortable arithmetic underneath every retirement-system debate. Longevity and fertility are not separate problems; they are two sides of the same generational transfer. The longer the old live, the more they draw down; the fewer the young, the less there is coming in. And the gap between the two is widening in every developed economy at once.
Two systems one squeeze
Pension offerings around the world divide into two basic designs, and aging hits each one differently. Defined-benefit plans promise a predetermined income for life; their sponsors carry the risk that retirees will live longer than projected, because the liability simply keeps growing with every birthday. Defined-contribution plans, by contrast, shift that risk onto the individual: the retiree draws down whatever the accumulated savings and investment returns support, and the real danger becomes outliving the money.
The distinction matters because the failure modes are opposite. A defined-benefit fund is squeezed from the liability side — it has promised more years of payments than the contributions can cover. A defined-contribution member is squeezed from the asset side — the pool of money runs out before the person does. In both cases, the pressure lands on investment performance, because the only variable a fund can move is the return it earns on what it holds. That is why the demographic crunch is, at its core, an investment story. Funds that once managed contributions into a predictable retirement now have to manufacture returns large enough to close a shortfall that nobody fully priced in a generation ago.
The numbers underneath
The scale of the challenge is laid out in the 2026 Marsh CFA Institute Global Pension Index, a survey of 55 retirement systems that is among the most widely cited baselines in the industry. The headline findings are blunt. Of the 55 systems covered, 43 have fertility rates below the replacement threshold of 2.1 children per woman — the level at which a population sustains itself without migration — and 23 sit below 1.5, a zone that demographers consider structurally difficult to reverse. The longevity side is equally stark. Life expectancy at age 65 in the more developed regions has risen 50.9% since 1950, to roughly 20 additional years. A retirement benefit that was designed to last a decade or so must now stretch across two. Every additional year multiplies across millions of beneficiaries, and the cumulative liability compounds in ways that are easy to understate in a single statistic.
The dependency ratio is the cruelest of the metrics. Looking 30 years out, the index projects how many people aged 70 and above will sit atop every 100 people aged 15 to 69. In several countries that ratio is set to roughly double. "The funding of future pensions and aged care both become more critical as the ratio of workers to retirees continues to decline," the report warns, before delivering the line that should sober every finance minister: "Very few systems, as they currently operate, are secure." The vulnerability is most acute for pay-as-you-go systems, in which the contributions of today's workers largely fund the benefits of today's retirees. Such schemes were built on the assumption of a growing workforce. When the workforce shrinks, the math inverts: fewer payers, more claimants, and no accumulated assets to absorb the difference. The design works brilliantly in a young, growing population and fails quietly in an old, shrinking one.
The United States is the clearest test case. The Old-Age and Survivors Insurance Trust Fund, which finances retirement and survivor benefits for tens of millions of Americans, is projected by the Social Security trustees to exhaust its reserves in the fourth quarter of 2032. That date has moved closer in nearly every annual report, and the political system has responded with the usual combination of inertia and denial. The trust fund's exhaustion would not mean benefit checks stop — payroll taxes would still fund roughly three-quarters of scheduled benefits — but it would force an immediate, across-the-board reduction unless Congress acts. Eight years is not long on a demographic clock.
The fully funded illusion
It would be comforting to believe that countries with accumulated, invested pension assets are immune. They are not. Fully funded schemes — which invest contributions from workers and employers to pay for future retirement — face a different but equally structural problem: the transition from accumulation to drawdown. As members retire and begin taking benefits, a growing number of mature funds are reaching the point where benefit outflows exceed the contributions still coming in. The index cautions that this crossover, once crossed, only widens. "Future benefit outflows will exceed the level of contributions or premiums," the report states, "and this financial strain will inevitably grow in the future."
When a fund pays out more than it receives, it has two choices. It can sell assets to meet obligations, which forces decisions about liquidity and sequencing. Or it can try to earn a higher return on what it keeps, which means taking on more risk. Neither choice is comfortable, and both are being made in real time across the developed world. Australia is an early, visible example. The Australian Prudential Regulation Authority reports that roughly a third of the country's superannuation funds recorded negative natural cash flows from assets over a three-year period — meaning, in plain language, that benefit payments exceeded contributions for a sustained stretch. Australia is younger than most of Europe and has a mandatory, well-funded retirement system, yet the crossover has already arrived for a meaningful share of its funds. The same transition is coming to every mature market, on a lag.
Rethinking risk
The demographic pressure is reshaping how pension funds invest, and the direction of travel is toward risk. To meet growing obligations with a shrinking contribution base, funds are reaching for higher returns — and higher returns, in the current market, live in private equity, infrastructure, and private credit. Betermier is direct about the trade-off. "You can try to earn higher returns on your investments," he says, "but that's going to require taking on greater levels of risk." The statement reads as a neutral observation, but it is a warning dressed in the language of portfolio theory. The risk being added is not the diversified, liquid risk of a broad equity index; it is the illiquid, concentrated, valuation-sensitive risk of unlisted assets whose mark-to-market is annual and whose exit depends on a functioning IPO and M&A market.
Jean-Pierre Aubry, associate director of state and local research at the Center for Retirement Research at Boston College, sees the shift across markets. "I think everybody is shifting a little more risk where they can," he says. "The costs are going up with this demographic shift." The U.S. state and local public-pension complex is among the most aggressive: data compiled by the Public Plans Database shows a substantial portion of those portfolios allocated to equities and private assets. Aubry argues that makes U.S. public funds considerably more exposed to investment risk than their counterparts in Europe and Canada, which lean more heavily on fixed income.
The asymmetry matters for taxpayers. When a public pension fund increases its allocation to volatile assets, it is not merely choosing a strategy; it is transferring the downside to the public balance sheet. If the private-asset bet pays off, benefits are funded. If it does not — and the drawdown phase leaves little time to recover — the shortfall lands on the general fund, which is to say on current and future taxpayers. The demographic crisis does not just threaten retirees; it threatens to become a fiscal crisis for governments that guaranteed the benefits.
The counterview
Not every pension manager reads the demographics as a mandate to gamble. David Elias, chief executive of the Australian fund Hostplus, argues that aging is only one of many factors shaping an investment decision, and that the durable answer is diversification, not concentration. Elias stresses holding a balanced portfolio across asset classes, geographies, and industries, while making sure that the expected return on any position adequately compensates for the risk being taken. The discipline sounds unglamorous next to the private-credit pitch, but it is the strategy that has kept mature funds solvent through previous drawdown transitions — and it is the strategy most at risk of being abandoned precisely when it matters most.
His larger point is that governments are not powerless. Immigration can replenish the working-age population faster than fertility can recover. Technological advances — from productivity gains to the automation of care work — can ease the burden that an aging population places on services. And demographic shifts themselves create investment opportunities, in healthcare, housing, and the businesses that serve older consumers. "I don't underestimate governments being incredibly creative in terms of dealing with these types of issues," Elias says. "But they're going to have to address it, no doubt about that."
The qualifier is the honest part. Creativity and good intentions do not change the arithmetic of a dependency ratio that is doubling. They change how the adjustment is distributed — whether it falls on retirees through lower benefits, on workers through higher taxes, on taxpayers through bigger deficits, or on investors through the returns they accept on retirement assets. The problem is not whether the adjustment happens; it is who absorbs it.
The generational ledger
Viewed coldly, the pension crisis is a transfer problem between generations that were never asked whether they wanted to be on opposite sides of it. The post-war cohort benefited from a demographic structure their own parents could only dream of: a broad tax base, rising productivity, and a retirement that most would outlive by only a few years. Their children and grandchildren face the mirror image: a shrunken contributor pool, a lengthening retirement, and a funding gap that has to be closed by someone.
The uncomfortable truth of every pension system is that it is a promise across time. Defined-benefit promises are explicit; defined-contribution promises are implicit. Either way, the money has to come from somewhere — from current workers, from future taxpayers, or from the returns on accumulated capital. When a system is underfunded, the adjustment does not disappear. It is simply pushed forward, and pushed-forward costs compound with interest.
That is the real meaning of the phrase "ticking time bomb." It is not that the systems will collapse tomorrow. It is that every year of delay makes the eventual correction larger, more painful, and more inequitable — because the burden falls hardest on the cohorts who are least able to absorb it: the young workers paying in, and the retirees who have the least time to adapt. For investors, the implications cut in several directions at once. The search for yield by pension funds is a structural bid under risk assets, and it is not going away. But it is also a source of fragility: when the largest, most patient capital in the world is forced to take more risk to meet fixed obligations, the margin for error shrinks everywhere. The same funds that are underpinning private markets today are the ones most likely to be forced sellers in a downturn, with all the liquidity cascades that implies.
There is also a question of sequencing that fund managers rarely discuss openly: the interaction between the drawdown transition and market cycles. A defined-contribution system works differently in accumulation than in decumulation. In the accumulation phase, contributions arrive on a schedule and fund managers can dollar-cost average through volatility, buying more when markets fall. In decumulation, the direction reverses — benefits must be paid on a schedule, and the fund becomes a forced seller of whatever it holds when the cash is due. The most dangerous time for such a fund is not a deep bear market; it is a shallow but prolonged one, because the fund cannot wait for a recovery it does not have time to reach. This is the operational reality beneath the glossy allocation charts, and it is why mature funds are so sensitive to the mix of liquid and illiquid assets they hold.
What to watch
The demographic clock is slow, but the markers it will hit over the coming decade are specific and dated. Watch these five.
First, the U.S. trust-fund countdown. The projected 2032 exhaustion of the Old-Age and Survivors Insurance Trust Fund is a fixed point on the calendar. Every passing year without legislative reform moves the day closer and makes the eventual fix more abrupt. The next trustees' report will show whether the line is holding or accelerating. Second, the drawdown crossover. Australia's negative-cash-flow funds are the leading edge of a transition that every mature defined-contribution market will face. Watch the share of funds in any given country that are paying out more than they take in. That number, more than any single index level, measures how fast the transition is arriving.
Third, the risk allocation. The shift toward private equity, infrastructure, and private credit is a slow reallocation that is hard to reverse quickly. Watch whether funds begin to demand more liquidity, or whether the search for yield continues to push allocations into ever more illiquid structures. The direction tells you how confident funds are in their own assumptions. Fourth, the policy response. Immigration policy, retirement-age legislation, and automatic-benefit-adjustment rules are the levers governments actually have. The French experience with pension reform — street protests, political paralysis, and a fiscal position that keeps deteriorating — is a preview of what happens when the adjustment is postponed rather than managed. Fifth, the investment opportunity in aging itself. Healthcare, housing for older populations, and the businesses serving longer lives are among the few areas where the demographic headwind is actually a tailwind. For funds willing to look past the liability, the same trend that is straining pension finances is creating durable demand elsewhere.
The quiet renegotiation
The pension crisis is best understood not as an event but as a renegotiation — a slow, decades-long rewrite of the social contract between generations. The old assumption, that each cohort would be supported by a larger one behind it, has been invalidated by the very success of modern medicine and the very choices of modern families. Nobody planned for a world in which people routinely live twenty years past retirement while their children have one or two children of their own.
That world is here, and the systems built for its opposite are being forced to adapt in real time. Some will adapt by taking more investment risk; some by cutting benefits; some by raising taxes; and some, inevitably, by a combination of all three that no politician has yet been willing to propose out loud. The one path that does not exist is doing nothing, because doing nothing is itself a choice — a choice to let the burden fall on whichever generation is least able to object.
The investors who will navigate this best are the ones who treat it not as a headline to be avoided but as a structural fact to be priced. Longevity risk, fertility decline, and the fiscal consequences of both are now permanent features of the investment landscape. The funds that acknowledge the trade-off — that the return on capital must compensate for the risk of a longer, less funded retirement — will be the ones that survive the drawdown. The ones that pretend the mathematics will change on its own will find that biology does not negotiate.
Complete digital access to quality Glebors financial topic with expert analysis from industry leaders.
Glebors Financial Become an Glebors subscriberMake informed decisions with the Glebors.Keep abreast of significant corporate, financial and political developments around the world. Stay informed and spot emerging risks and opportunities with independent global reporting, expert commentary and analysis you can trust.
"Insight of the global economy, dig into more ideas, analyze the global financial dynamics and the risks of political situation from a strategic, scientific and rational perspective, based on economic data and more than 20 years of financial intelligence."
If you want to know more details to provide support for your investment and business activities, this financial report that we have selected for you can give you what you want, please subscribe to read it. Glebors Global Finance aims to provide business elites and decision makers with daily business news, data interpretation, in-depth analysis and commentary.
Glebors Global Finance's amount of financial information digs into deeply major events and economic data that have a huge impact on the global economy, based on in-depth industrial research and special reports, with a truly global perspective. Financial reports have become "must-read" financial information for senior managers. Glebors Global Finance currently has more than 2.85 million Chinese readers and more than 3.5 million overseas readers, including more than 600,000 high-end member readers.
We are not gonna make spamming